A Spammy Innovation

You have to be impressed with the bad-guys/girls who come up with new ways to try to separate you and your money. I got this email a few days ago letting me know that I had 2 days to buy bit coins and send them to their wallet. Well 2 days have come and gone and I am sad to say that the promised porno-site has yet to materialize. Nevertheless I am happy to share the brilliant bit of Spoofing put on by this determined bad guy/girl.

The Email (My Comments in Italics)

You may not know me and you are probably wondering why you are getting this e mail, right?
I’m a hacker who cracked your email and devices a few months ago.

Do not try to contact me or find me, it is impossible, since I sent you an email from YOUR hacked account.
I setup a malware on the adult vids (porno) web-site and guess what, you visited this site to have fun (you know what I mean). [Do kittens playing with yarn balls count as a porno site?]
While you were watching videos, your internet browser started out functioning as a RDP (Remote Control) having a keylogger which gave me accessibility to your screen and web cam.
After that, my software program obtained all information.

You entered a passwords on the websites you visited, and I intercepted it.
Of course you can will change it, or already changed it.
But it doesn’t matter, my malware updated it every time.
What did I do?

I backuped device. [Back ups are important, good for you!] All files and contacts.
I created a double-screen video. 1st part shows the video you were watching (you’ve got a good taste haha . . .)[Thank you, I like a good kitten/yarn video], and 2nd part shows the recording of your web cam.
exactly what should you do?
Well, in my opinion, $1000 (USD) is a fair price for our little secret. You’ll make the payment by Bitcoin (if you do not know this, search “how to buy bitcoin” in Google).
My Bitcoin wallet Address:
1MT6jgF7YS7SDpuQfVHe6sEC8W7PxrwEH4
(It is cAsE sensitive, so copy and paste it) [You are very considerate to provide this information]

Important:
You have 48 hour in order to make the payment. (I’ve a unique pixel in this e mail, [YIKES, AN unique pixel] and at this moment I know that you have read through this email message).
To track the reading of a message and the actions in it, I use the facebook pixel. [My GOD you are sophisticated, a FACEBOOK Pixel]
Thanks to them. (Everything that is used for the authorities can help us.) If I do not get the BitCoins, I will certainly send out your video recording to all of your contacts including relatives, coworkers, and so on. [Please do, they also like a good Cat Video – here is the best of 2018 – www.youtube.com].

Be Careful Out There

I sent the Polish internet provider (retsat1.com.pl) a copy of the email so hopefully some poor infected user can get their anti-virus updated.

Apparently this scam is about six months old (hmm, I appear to be a late adopter of being targeted) but the messages are the same.  Strong passwords, don’t put things like your real birthday, name, etc. into social media (Facebook, LinkedIn, etc.) and get a password tracking tool.

Read more: www.businessinsider.com.

The Bus Chronicles

New Year’s resolutions are dangerous affairs, so dangerous that most people quickly abandon them for the familiar arms of bad habits. It is with this in mind that I am sharing my resolution: I no longer plan to drive to work.  Dear boss, don’t worry, I am planning on coming to work just that I don’t plan to drive there.

The Motivations on the Bus Go Round and Round …

There are of course a number of reasons to not drive:

  1. Concern about climate change and reducing your carbon foot print;
  2. Unable to drive for reasons beyond one’s control (blindness, illness)
  3. Unable to drive for reasons in your control due to poor choices (drunk driving, loss of a license)
  4. Trying to save money. 
  5. Other reasons.

I am comfortable enough with my parsimonious-ality to let you know my motivation is a combination of numbers #4 and #5. As for the other reasons (#1), I doubt my little Ford Ranger will make that much of a difference to climate change as compared to the 259 NEW GW of coal-fired generation plants China is bring online.  Fortunately I am both capable and legally allowed to drive (#2 and #3).  Besides, like the vast majority of people, I am an above average driver!

Transit Snobbery 

Having just come back from Vienna with a world class transit system, I will be using a system that is definitely middle of the road.  Not chickens in cages seated next to me but definitely not at the Western European standard either.  My son swore off the bus when going to University with horror stories of them blowing past waiting passengers at bus stops, arriving late, excessively early and surly drivers.  Hopefully my adventures are more pleasant.  

U2 U-Bahn (metro) crossing the Danube heading into Vienna City Center

The Economics of the Bus

 But back to my motivations and the first is economics and while the cash flow is positive it is not great, here is how driving versus the bus stacks up:

Factor Driving Bus
Bus Pass per Month – 116.00
Gas Costs*/Month 130.00 –
Parking Pass**/Month 126.15 –
Insurance/Maintenance $$$ –
Total Cost 246.15 116.00
Cost per Work Day$$ 12.30 5.80
Driving time # 30-45 minutes/day 60-90 minutes/day
  • * I get about 7km/litre and have a ~45km commute per day.  Assuming $1.00 per litre (currently gas is as $0.90) this works out to $115 – $120/day.
  • ** Technically I don’t pay for parking but I am charged a taxable benefit of $145/bi-weekly.  Assuming a 40% marginal tax rate this results in a cash cost of $126.15/month.
  • # These are highly variable, I have gotten to work on a quiet Sunday in 20 minutes and other times it has taken me 2 hours to get home due to the weather.  Overall though, I suspect that the impact on time will be a bit of a wash of driving over transit.
  • $$$ I haven’t calculated this yet, see failing fast below before I change my insurance.

Assuming 20 work days per month ($$), the difference in cost is about $6.50/day or about $130.00 per month or perhaps a grand a year.  Mehhh, not really big enough money to be spending 100% more time in my commute, so why would anyone want to give up a comfy(ish) Ford Ranger for a bus?

Reading, Riding and A-Rhythmic-Meditation

My motivation is the 3.2km walk from my house to the bus depot.  3,200 metres in the morning is about 3,000 steps (of a suggested 10,000 per day total) and 40 minutes in walking meditation.  Once on the bus , I plan to read.  While I can listen to books in my vehicle, taking notes while driving is not recommended.  There is also something peaceful about letting someone else worry about the stop and go of traffic while you either read or stare into middle space.  Finally, the most important reason involves a bike. 

I hope to bike commute more this year.  Not having a parking pass is like burning my boats; there is no going back!  Okay, I can pay for expensive day parking but that metaphor is not nearly as good as smoldering boats.  

Wish Me Luck and Failing Fast

So that is my new year’s resolution and given that I just dropped $116 on a pass to get started.  If I can get through January, then February should be easier, etc..  Wish me luck and if not, see you on the road in February.   

Business Process Documentation or Borrowing from Sheffield

What is the role of business process mapping to internal controls? The Sheffield model outlines various purposes for mapping, including clarity, compliance, process improvement, and training. The Sheffield University guidance provides a structured approach to process mapping, with different levels and options for each purpose, emphasizing the importance of accurate documentation.

Continue reading →

Costs-Benefits of Public Sector Audit Recommendations

Last week I attended a conference involving finance and administration professionals from international organizations based in Vienna Austria.  One of the side conversations that came up was managing an increasing number of audit recommendations with diminishing resources.

Public Sector versus For-Profit Auditor

There are important differences to note of the audit universe of the public sector.  For a for-profit organization, the auditor is a service another for-profit organization provides on the behest of the board and to provide assurance to the shareholders.  Even for non-profit organizations, this relationship exists – there is an inherent value for money question.

In the public sector, this relationship not only is absent but may also be perverted.  There can be an incentive of an auditor general (and its equivalents) to make comments on the public sector so as to justify the continuing existence of the auditor general.  Worse still is a ‘lime-light auditor’ who enjoys the unveiling of recommendations and the hero culture that can accrue to the auditor as a result.

The above of course is a worst case and the vast majority public sector auditors are dedicated and competent professionals with the tax payers and citizen’s interest in mind.  In addition, auditors have uncovered waste and have been effective change agents to ensure the best possible civil service for a political entity.  Alas, the vast majority are so but not all – and thus the question of how the value for money question can be applied to a public sector audit?

The Audit as a Rationale and Rotational Process

It is easier to make an audit comment (observation, recommendation, etc.) than it is to implement them.  As the public sector becomes more strapped for resources, it must balance the new audit comment against current operations, projects, public policy changes or even completing past audit recommendations.

Part of this challenge is that the public sector is abysmal at estimating the costs and the resulting benefits of operations or new initiatives.  A for-profit organization is laser focused on current operations costs.  If revenue cannot change, then costs must drop to sustain or improve the bottom line.  Alternatively, if a new project does not result in new revenue or other benefits (lower costs, regulatory compliance, operational effectiveness, etc.) then it is dropped in favour of a different investment.

The Public Sector does not always share the same rationality.  The primary financial discipline comes from the allocated budget and not overall profitability.  Additionally, public sector auditors reach into wider areas of the organization (as they should) resulting in recommendations that go far beyond the financial statements.

To go into these wider areas, public audit entities may engage outside expertise (e.g. an IT security audit firm) or they offer long-term employment to develop broad public sector expertise.  The problem with the second strategy is that there may not be enough turn over of the public sector audit organization that parallels the effect of firm rotation in the private sector world.

The Price of a Recommendation

Given the nature of both the auditors and the audit engagement are different in the public sector should not the output also be different?  How about pricing each audit suggestion (recommendation, observation, etc.)?

The auditor and management would independently develop an estimated number of hours and associated costs to implement a recommendation.  The auditor would use its larger experience from other Ministries, organizations etc. and the organization based on its insider experience.  The cost should be a full cost as if whatever is being implemented is entirely done so by a third-party with the same knowledge as current management.  For example, if there is a recommendation to perform an additional verification of a payment voucher, the cost would be as if a contractor is engaged to come in and do the verification.

The reason for this third-party approach is to avoid the pitfall of ‘wishing away the problem’.  Thus an auditor could say that the check is nominal by the payments clerk and therefore there is no cost.  In contrast, management knows that they payment clerk is doing other activities that the auditor is not factoring in and thus the cost is not free.

The auditor and management would ideally compare and agree to a high-low range of cost to implement.  These costs would be aggregated and the total cost of audit comments would be estimated (once again in a range).  The actual costs of implementation (both project and run-costs) would be reported against the past audits.  This reporting would help to fine-tune the estimations and provides a comparison point for other audit engagements.  Thus in the above example, the auditor could state that implementing an additional check in other organizations typically consumes 10-20 hours of additional effort per week as compared to management’s assertion that it would take 15-30 additional hours per week.

Pricing and Gaming the Auditor General’s Report

The above cost methodologies can be aggregated and reported as a companion piece of information with the respective audit reports.  Currently such reports provide a bias view of the recommendations.  The auditor general will list numerous infractions and the hundreds of changes they are proposing.  Implicit in this list is that these are things the public sector organization should have thought of long ago.  By pricing the suggestions it balances the report so that the public knows that perhaps a change was not done because the benefits do not exceed the costs.

The problem with applying a cost to something is that there is a risk of it being gamed.  The auditor wishing away the costs and management overestimating.  Thus the importance of the comparison function and a longer-term comparison of how good the estimates are from both the auditors and management.

Thoughts, should a public sector auditor price their recommendations?  Leave me a comment or drop me a note with your views.


MCEFing the Gap – Introduction

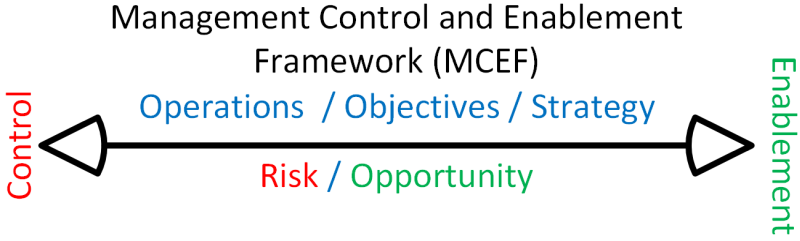
Organizations are created to achieve objectives of a board of directors or the equivalent.  The challenge has been how to enable an organization but also protect the resources entrusted to it by its owners.  That is, how do you both Control and Enable an organization? The COSO Framework frames the question of Control but does not address the other side of the coin, things like employee-motivation, capitalizing on opportunities, customer service or the outcomes of public policy.  These are examples of what I call ‘Enablement’.

Continue reading →

COSO – Mind the Gap

The author completed a COSO certification course, appreciating its quality despite previous frustrations with online learning. However, the course fell short in addressing the practical deployment of COSO, leaving gaps in internal-control specifics. Nonetheless, COSO promotes adaptability for organizations, suggesting they can customize the framework to better suit their needs.

Continue reading →